A signed contract is an exciting milestone, but the path from accepted offer to keys includes several important financial checkpoints. Understanding earnest money, appraisal results, and closing documents can help Buford buyers and sellers move through the transaction with clearer expectations, better questions, and fewer last-minute surprises.
Earnest Money Sets the Contract in Motion
Once a home purchase offer is accepted, earnest money is usually one of the first deadlines on the calendar. This deposit shows the buyer’s good-faith intent to complete the purchase under the terms of the contract. In a Buford transaction, the amount, delivery deadline, escrow holder, and circumstances for a possible return of funds are all determined by the signed agreement—not by a one-size-fits-all rule.
It helps to think of earnest money as a contract-controlled deposit rather than an extra closing fee. The funds are generally held in an escrow account and are typically applied toward the buyer’s cash due at closing if the sale moves forward. Buyers should confirm exactly where the funds must be delivered, how they may be paid, and when proof of delivery is needed. Waiting until the final day can introduce unnecessary stress, particularly when bank processing times or wire-verification procedures are involved.
Sellers benefit from understanding this timeline as well. A timely deposit is one signal that the contract is progressing, but it is still only one piece of the overall transaction. Inspection periods, financing contingencies, title work, lender underwriting, and appraisal requirements continue on their own schedules. Keeping a written timeline of contract dates makes it easier for everyone to see what has been completed and what still needs attention.
The earnest-money deadline is often only a few business days after acceptance. Confirm escrow instructions through a trusted, independently verified contact method before sending any funds.
Whether earnest money is refunded, credited, or potentially disputed depends on the language of the contract and what occurs during the contingency periods. For example, a buyer may have defined options related to inspections, financing, appraisal, or other negotiated conditions. No one should assume the outcome based on a verbal understanding. Review the agreement carefully, keep written records, and ask the closing professional or real estate agent to explain the next contractual step when a deadline or condition changes.
How the Appraisal Fits Into a Buford Purchase
An appraisal is an independent opinion of a property’s value, commonly ordered by the lender when financing is involved. It is different from an inspection: an inspection focuses on the home’s condition and visible systems, while an appraisal helps the lender evaluate the property as collateral for the loan. Appraisers consider the home’s features, condition, location, recent comparable sales, and prevailing market data available at the time of the report.
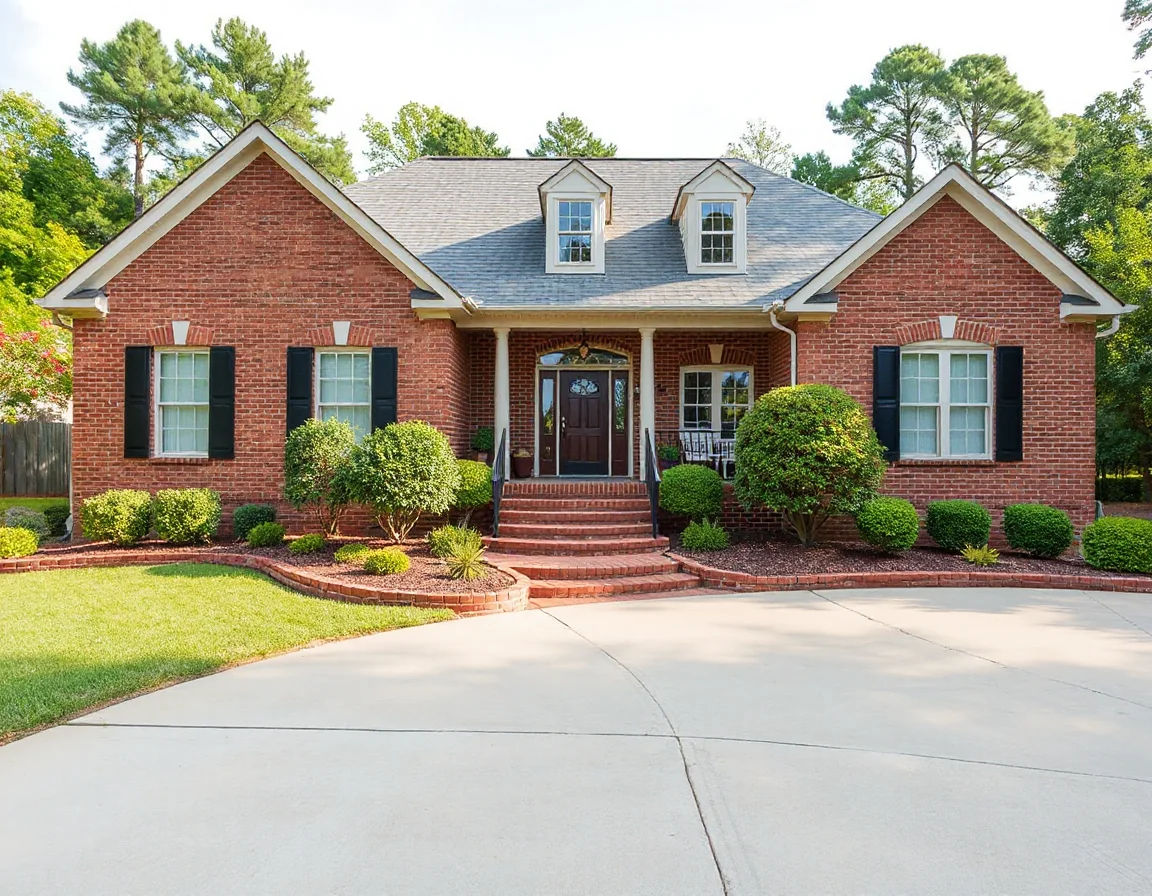
A strong appraisal result does not necessarily mean the report will match every expectation about a home’s value. The appraiser works from established methodology, and the lender reviews the report in relation to the loan amount and contract terms. If the appraised value meets or exceeds the purchase price, the financing process may continue without an appraisal-based adjustment. There can still be other lender conditions to satisfy, including income, asset, insurance, and title documentation.
If the appraisal comes in below the agreed purchase price, the parties usually need to revisit the contract’s appraisal provisions. Depending on the specific terms and the choices available to the buyer and seller, potential paths may include renegotiating the price, changing the buyer’s cash contribution, challenging factual errors in the report through the lender’s process, or proceeding another way allowed by the agreement. A lower-than-expected appraisal is not automatically the end of a transaction; it is a moment for careful review and prompt communication.
For sellers, preparation can make the appraiser’s visit more efficient. A concise list of recent improvements, permits when applicable, major system updates, and notable property features can help ensure details are available. The list should be factual and should not attempt to direct the appraiser’s value conclusion. Buyers can also stay grounded by remembering that appraisal timing may affect the loan schedule, especially when additional lender review is needed.
An appraisal and inspection answer different questions. Keeping both reports, their deadlines, and any follow-up requests organized can prevent a small delay from becoming a closing-date issue.
Closing Day Is a Review Process, Not Just a Signature Session
Closing brings together the lender’s final figures, title work, insurance confirmation, contract terms, and required signatures. In the days leading up to settlement, buyers commonly receive a Closing Disclosure that outlines loan terms, projected payments, closing costs, cash needed to close, and other important details. Reviewing it early gives buyers time to compare the figures with prior estimates and ask questions about changes.
Buyers should also plan for the final walk-through, which is typically scheduled shortly before closing. This is an opportunity to confirm that the property is in the condition required by the contract, agreed-upon items remain, and negotiated repairs or credits have been addressed as documented. It is not a new inspection or a chance to reopen every issue, but it is an important practical step before ownership transfers.
Sellers should prepare to provide any items required by the contract or closing attorney, such as keys, garage remotes, access devices, manuals, repair receipts, or payoff information for existing loans. Leaving the home in the agreed condition and removing personal property on schedule can help avoid a rushed final conversation. Utility transfer arrangements, insurance timing, and possession terms should also be confirmed in writing rather than assumed.
Wire fraud awareness belongs on every closing checklist. Criminals can send convincing-looking messages with altered payment instructions. Before wiring funds, independently call a known telephone number for the closing attorney or settlement office and verify the instructions verbally. Do not rely on a phone number or link included in an unexpected email, text, or attachment.
A Clear Timeline Creates More Confident Decisions
The smoothest transactions are rarely the ones with no questions; they are the ones where questions are raised early and answered with the contract, lender documentation, and closing professionals in view. Earnest money confirms the initial commitment, the appraisal helps support the financing decision, and closing turns the contract into completed ownership. Each stage has deadlines, documents, and decisions that deserve attention.
For anyone buying or selling in Buford, a simple shared checklist can be invaluable: note every contingency date, save receipts and confirmations, review lender requests promptly, and communicate changes before a deadline passes. With organized preparation and experienced guidance, the final steps can feel much more manageable than the stack of paperwork might suggest.